Your home is likely one of the biggest financial investments you’ll ever make. Whether you own a house, condominium, duplex, or townhouse, protecting it from unexpected events should be a top priority. That’s exactly where home insurance comes in.
Many homeowners purchase insurance simply because their mortgage lender requires it. Others buy a policy believing it covers every possible disaster. Unfortunately, both assumptions can lead to costly misunderstandings.
Home insurance is designed to protect your property and finances, but it doesn’t cover every type of damage or loss. Every policy has coverage limits, exclusions, and conditions that determine when the insurance company will—and won’t—pay a claim.
Understanding these details before disaster strikes can save you thousands of dollars and prevent unpleasant surprises when you need financial protection the most.
In this complete guide, we’ll explain how home insurance works, what it typically covers, what it usually excludes, how claims work, common mistakes homeowners make, and practical tips for choosing the right policy.
What Is Home Insurance?
Home insurance (also called homeowners insurance) is a contract between you and an insurance company. In exchange for paying regular premiums, the insurer agrees to help cover certain financial losses caused by covered events such as fire, theft, storms, or vandalism.
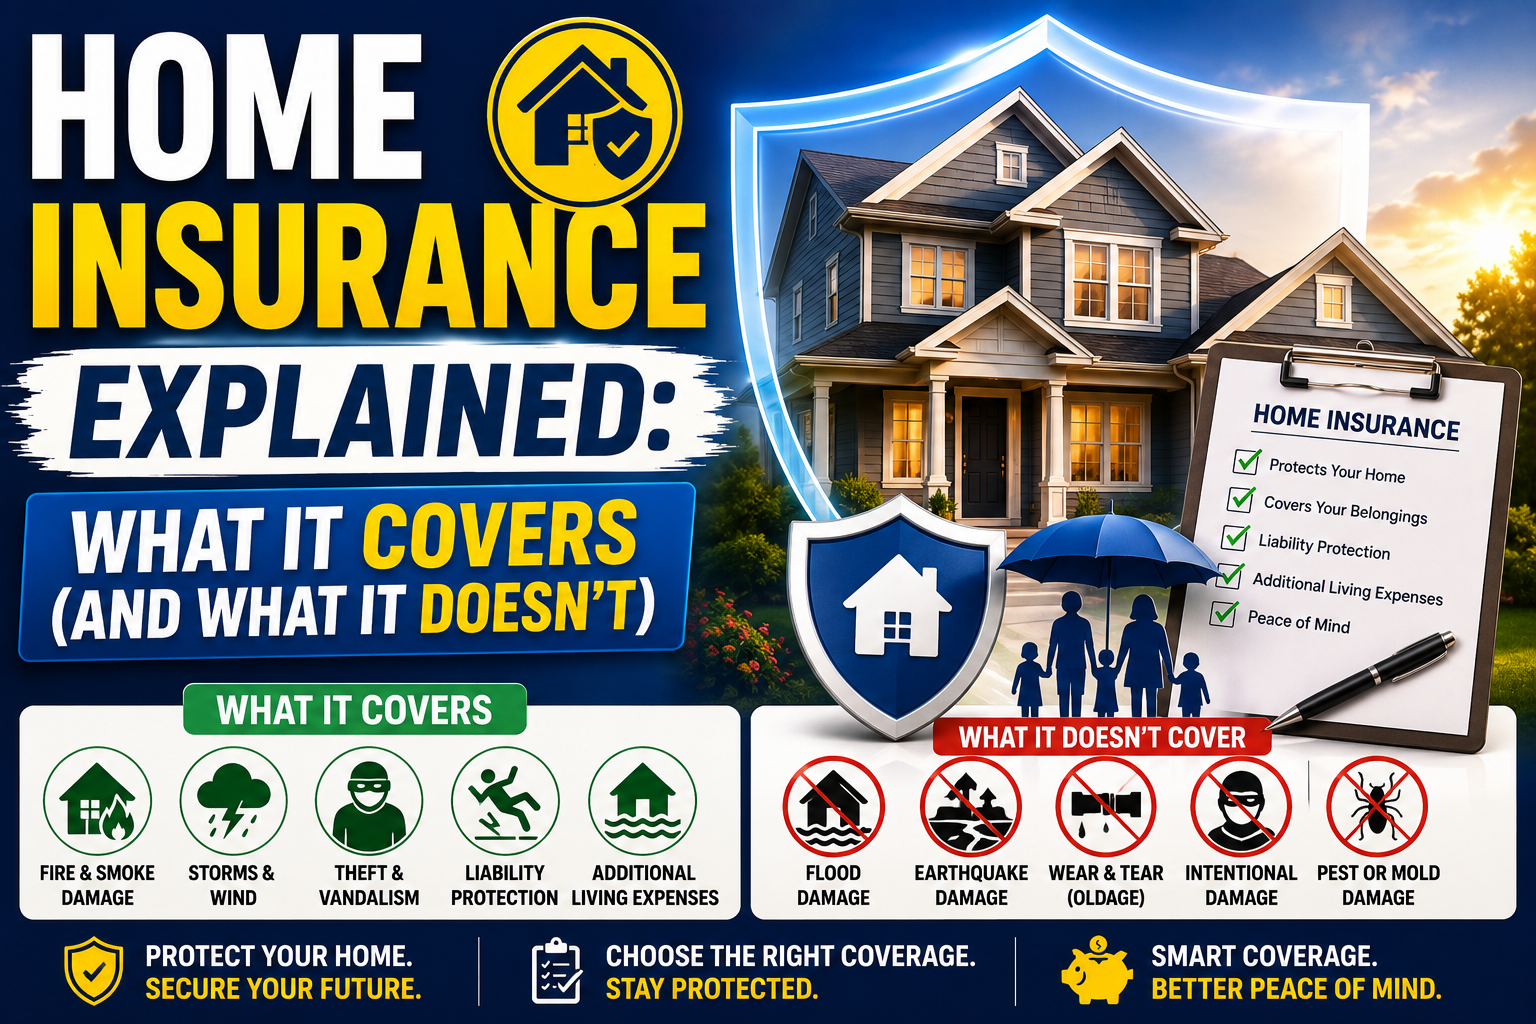
A standard home insurance policy generally protects:
- Your home’s structure
- Attached structures
- Personal belongings
- Liability claims
- Additional living expenses after a covered disaster
The exact coverage depends on your policy and insurer.
Why Home Insurance Is Important
Many homeowners underestimate the financial impact of a major disaster.
Imagine experiencing:
- A house fire
- A burglary
- Storm damage
- A fallen tree
- Water damage
- Someone getting injured on your property
Repairing or rebuilding your home could cost tens or even hundreds of thousands of dollars.
Without insurance, those expenses would come directly from your savings.
Home insurance provides financial security during unexpected events and helps homeowners recover more quickly.
What Does Home Insurance Cover?
Although coverage varies by provider, most standard home insurance policies include several key protections.
1. Coverage for Your Home’s Structure
This is often called dwelling coverage.
It helps pay to repair or rebuild your home if it’s damaged by a covered event.
Examples include:
- Fire
- Lightning
- Windstorms
- Hail
- Explosion
- Smoke damage
- Vandalism
- Falling objects
Covered parts of the home generally include:
- Roof
- Walls
- Floors
- Windows
- Built-in cabinets
- Plumbing
- Electrical systems
If rebuilding costs increase due to inflation or construction costs, make sure your policy limits remain adequate.
2. Coverage for Other Structures
Many homeowners forget that insurance may also protect structures separate from the main house.
Examples include:
- Detached garages
- Fences
- Storage sheds
- Gazebos
- Guest houses
- Workshops
Coverage limits are usually a percentage of your dwelling coverage.
3. Personal Property Coverage
Home insurance often protects your personal belongings if they’re damaged or stolen.
Covered items may include:
- Furniture
- Clothing
- Electronics
- Appliances
- Jewelry (subject to limits)
- Kitchen equipment
- Books
- Sports equipment
For valuable possessions such as expensive jewelry, artwork, or collectibles, additional coverage may be necessary.
4. Liability Protection
Liability coverage helps protect you if someone is injured on your property or if you accidentally cause damage to someone else’s property.
Examples include:
- A visitor slips and falls.
- Your child accidentally damages a neighbor’s property.
- Your dog bites someone (depending on the policy).
Liability coverage may help pay:
- Medical expenses
- Legal fees
- Court judgments
- Settlement costs
This is one of the most valuable parts of a homeowners insurance policy.
5. Additional Living Expenses (ALE)
If your home becomes uninhabitable because of a covered event, your insurance may help pay for temporary living expenses.
This could include:
- Hotel stays
- Rental accommodation
- Restaurant meals
- Laundry expenses
- Transportation costs
Coverage typically continues until your home is repaired or rebuilt, subject to policy limits.
Common Events Usually Covered
Most standard policies protect against sudden and accidental events such as:
- Fire
- Smoke
- Lightning
- Theft
- Vandalism
- Windstorms
- Hail
- Explosions
- Falling trees (under certain conditions)
- Damage caused by aircraft or vehicles
- Certain plumbing accidents
Coverage depends on your policy wording.
What Home Insurance Usually Does NOT Cover
One of the biggest mistakes homeowners make is assuming every disaster is covered.
In reality, several common events are often excluded.
1. Flood Damage
Standard home insurance typically does not cover flooding caused by:
- Heavy rainfall
- Overflowing rivers
- Storm surges
- Flash floods
Flood insurance often requires a separate policy.
If you live in a flood-prone area, this additional protection may be essential.
2. Earthquakes
Damage caused by earthquakes is usually excluded from standard homeowners insurance.
Separate earthquake insurance is often available.
3. Wear and Tear
Insurance is designed for sudden, accidental losses—not gradual deterioration.
Examples not usually covered include:
- Aging roofs
- Rust
- Mold caused by neglect
- Pest damage
- Rot
- Normal maintenance issues
Routine maintenance remains the homeowner’s responsibility.
4. Intentional Damage
Insurance generally won’t pay for damage intentionally caused by the homeowner.
Fraudulent claims can result in denied claims, policy cancellation, and legal consequences.
5. Certain High-Value Items
Policies often limit payouts for expensive belongings such as:
- Jewelry
- Fine art
- Rare collections
- Luxury watches
- Cash
- Precious metals
If you own valuable possessions, ask about scheduled personal property endorsements.
Understanding Deductibles
A deductible is the amount you agree to pay before your insurance begins covering an eligible claim.
Example:
Damage repair costs: $15,000
Your deductible: $1,000
Insurance pays: $14,000
You pay: $1,000
Policies with higher deductibles often have lower monthly premiums, but ensure you can comfortably afford the deductible if you need to file a claim.
How the Claims Process Works
If your home suffers covered damage, follow these general steps:
Step 1
Protect your property from additional damage if it’s safe to do so.
Step 2
Notify your insurance company immediately.
Step 3
Take photographs and videos of all damage.
Step 4
Create a list of damaged belongings.
Step 5
Keep receipts for emergency repairs.
Step 6
Meet with the insurance adjuster if required.
Step 7
Review the settlement offer carefully before accepting.
Good documentation often speeds up claim approval.
Common Mistakes Homeowners Make
Avoid these expensive errors:
Buying Insurance Based Only on Price
Cheaper policies may provide significantly less protection.
Underinsuring the Home
Ensure your coverage reflects rebuilding costs—not just market value.
Forgetting to Update Coverage
Renovations and home improvements often increase replacement costs.
Ignoring Policy Exclusions
Understand what’s excluded before disaster strikes.
Not Keeping an Inventory
Photographs and a home inventory make claims much easier.
Tips for Choosing the Right Home Insurance Policy
When comparing policies, consider:
- Coverage limits
- Deductibles
- Exclusions
- Additional endorsements
- Claim settlement reputation
- Customer reviews
- Financial strength of the insurer
- Customer support quality
Don’t focus solely on the premium.
A slightly more expensive policy may provide significantly better protection.
Ways to Save Money on Home Insurance
You don’t have to sacrifice protection to reduce costs.
Consider these strategies:
- Bundle home and auto insurance.
- Install smoke detectors.
- Add security systems.
- Increase your deductible (if affordable).
- Maintain your home properly.
- Compare quotes annually.
- Ask about available discounts.
Responsible homeowners often qualify for lower premiums.
Frequently Asked Questions (FAQs)
Does home insurance cover theft?
Yes, most standard homeowners insurance policies cover theft of personal belongings, subject to policy limits and conditions.
Does home insurance cover floods?
Usually not. Flood damage typically requires separate flood insurance.
Is roof damage covered?
Often yes, if caused by a covered event such as fire, hail, or windstorm. Damage from age or neglect is generally excluded.
Does home insurance cover mold?
It depends on the cause. Mold resulting from a covered event may be included, while mold caused by poor maintenance is generally excluded.
How much home insurance do I need?
Ideally, your policy should provide enough coverage to fully rebuild your home and replace your belongings if they’re destroyed.
Final Thoughts
Home insurance is one of the most important financial protections a homeowner can have. It helps safeguard your home, belongings, and financial future against unexpected events such as fire, theft, storms, and liability claims.
However, it’s equally important to understand what your policy doesn’t cover. Assuming every type of damage is included can lead to costly surprises when you need help the most.
Before purchasing or renewing your policy, take the time to review your coverage, understand the exclusions, compare multiple insurers, and ensure your coverage limits reflect the true cost of rebuilding your home and replacing your possessions.
The right home insurance policy isn’t simply the cheapest one—it’s the one that gives you confidence that, if disaster strikes, you’ll have the financial support needed to recover. Protect your home wisely today, and you’ll enjoy greater peace of mind for years to come.