Buying insurance is one of the smartest financial decisions you can make, but only if you choose the right policy. Whether you’re purchasing life insurance, health insurance, auto insurance, home insurance, travel insurance, or business insurance, asking the right questions before signing a policy can save you from expensive surprises later.
Unfortunately, many people buy insurance based on advertisements, recommendations from friends, or the lowest price they can find. While these factors may influence your decision, they shouldn’t be the only considerations. An insurance policy is a legal contract, and every policy has its own terms, conditions, exclusions, limits, and claim procedures.
If you don’t understand what you’re buying, you may discover important gaps in your coverage only after you need to file a claim—and by then, it may be too late.
The good news is that asking just a few thoughtful questions can help you make a more informed decision and ensure your policy provides the protection you expect.
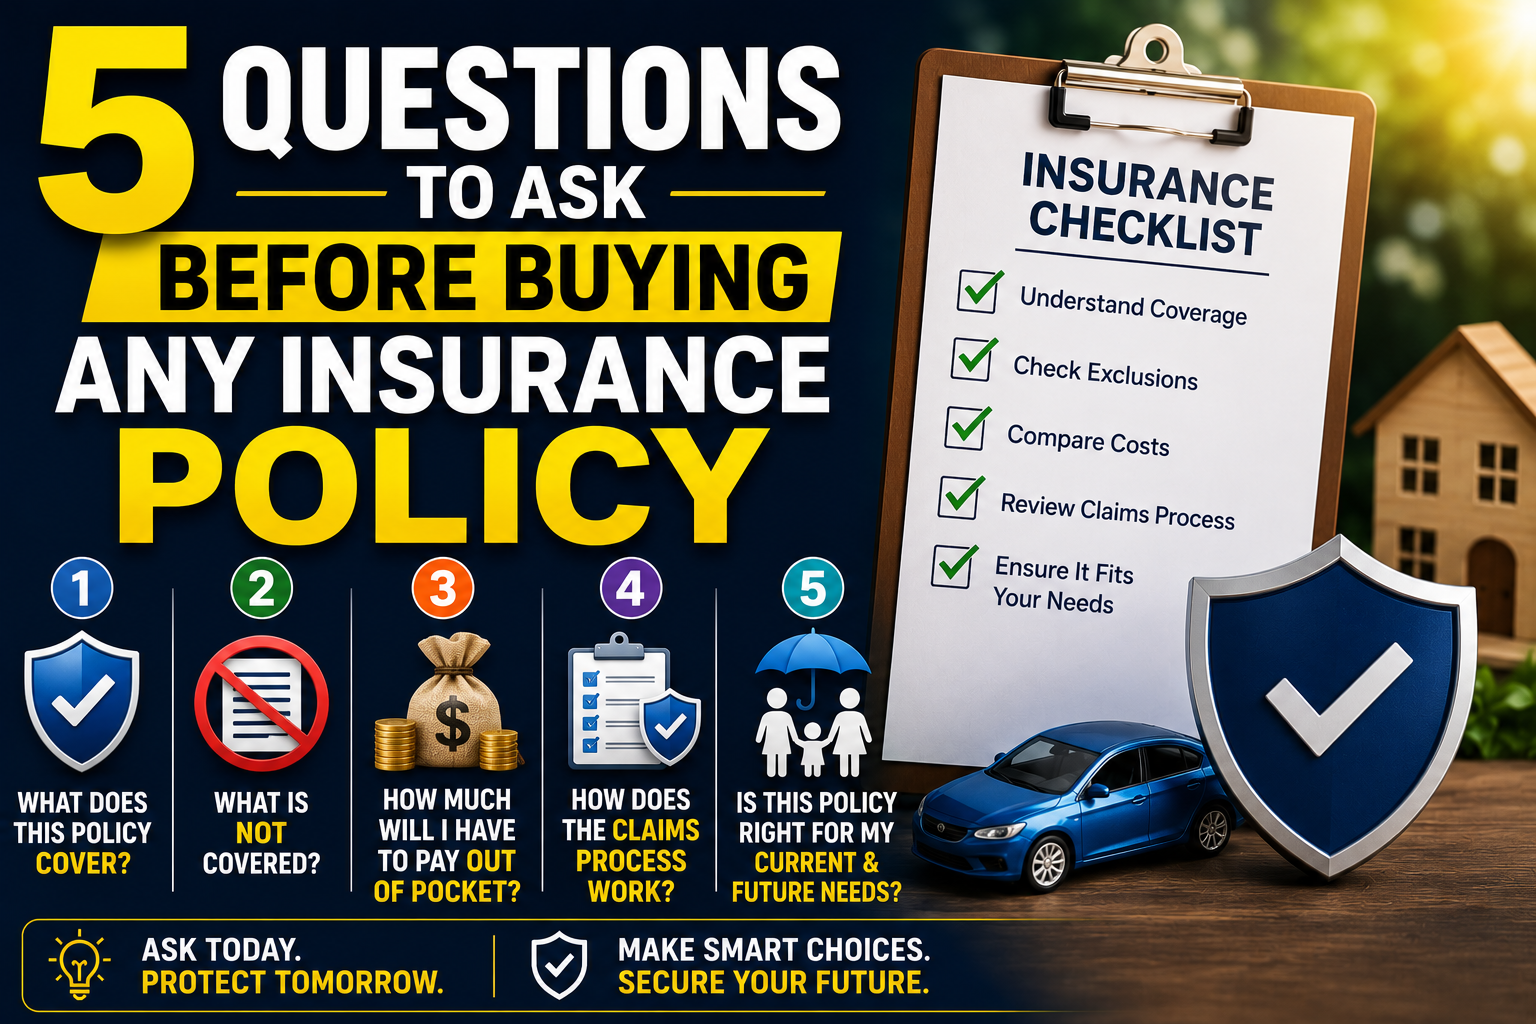
In this guide, we’ll explore the five most important questions to ask before buying any insurance policy, explain why each question matters, and provide practical tips to help you choose coverage that fits your needs and budget.
Why Asking Questions Matters
Insurance isn’t a one-size-fits-all product. The right policy for one person may be completely unsuitable for another.
By asking the right questions before purchasing coverage, you can:
- Avoid paying for unnecessary features.
- Identify gaps in coverage.
- Understand your financial responsibilities.
- Compare policies more effectively.
- Reduce the risk of claim denials.
- Save money without sacrificing protection.
Think of these questions as your checklist for making a confident insurance decision.
Question 1: What Exactly Does This Policy Cover?
This is the most important question you can ask.
Many people assume they know what’s included in an insurance policy, only to discover after an accident or emergency that certain situations aren’t covered.
Every insurance policy has a section outlining the events, services, or losses it will pay for. Understanding this section helps you know exactly what protection you’re purchasing.
For example:
- Does your health insurance include specialist visits, prescription medications, and emergency treatment?
- Does your home insurance cover fire, theft, floods, and natural disasters?
- Does your car insurance include collision, comprehensive, and liability coverage?
- Does your travel insurance cover trip cancellations and medical emergencies abroad?
Never rely on assumptions. Ask your insurer to explain the policy in plain language if anything is unclear.
Tip
Request a written summary of the coverage so you can compare it with other policies.
Question 2: What Is Not Covered?
Knowing what a policy excludes is just as important as knowing what it covers.
Every insurance policy contains exclusions—specific situations in which the insurer will not pay a claim.
Some common exclusions include:
- Intentional damage
- Wear and tear
- Pre-existing medical conditions (depending on the policy)
- High-risk activities
- Certain natural disasters
- Mechanical failures
- Cosmetic repairs
Imagine purchasing home insurance assuming it covers flood damage, only to discover after a flood that you needed a separate flood insurance policy.
That misunderstanding could cost thousands of dollars.
Ask questions such as:
- What exclusions should I be aware of?
- Are there optional riders to cover these exclusions?
- Are there waiting periods?
- Are there circumstances where claims are automatically denied?
Understanding exclusions prevents unpleasant surprises later.
Question 3: How Much Will I Have to Pay Out of Pocket?
Many buyers focus only on the monthly premium and ignore the other costs associated with a policy.
However, your total financial responsibility may include:
- Deductibles
- Co-payments
- Coinsurance
- Excess payments
- Coverage limits
- Claim processing fees (where applicable)
For example, a health insurance policy with a low monthly premium might have a very high deductible, meaning you’ll pay a substantial amount yourself before the insurer contributes.
Similarly, an auto insurance policy may require you to pay an excess amount after every claim.
Understanding these costs helps you avoid unexpected expenses during an emergency.
Important questions include:
- What is the deductible?
- Are there claim limits?
- Will I need to pay anything after filing a claim?
- Are there annual coverage caps?
Affordable premiums don’t always mean affordable insurance.
Question 4: How Does the Claims Process Work?
Insurance is only valuable if the claims process is smooth when you need it.
Before purchasing a policy, ask how claims are handled.
Key questions include:
- How do I file a claim?
- What documents will I need?
- How long does claim processing usually take?
- Is there a mobile app for claims?
- Are claims available online?
- Is customer support available 24/7?
- What situations commonly lead to claim rejection?
A company with a fast, transparent claims process can make a stressful situation much easier to manage.
Reading customer reviews can also provide valuable insight into an insurer’s claim experience.
Question 5: Is This Policy Right for My Current and Future Needs?
Your insurance needs today may not be the same in five years.
Think about how your life could change.
You might:
- Get married
- Have children
- Buy a home
- Start a business
- Change jobs
- Retire
- Purchase additional vehicles
Ask whether the policy allows you to:
- Increase coverage later
- Add family members
- Include optional riders
- Renew without difficulty
- Transfer benefits if needed
Choosing a flexible policy today may save you from purchasing a completely new policy later.
Bonus Questions Worth Asking
While the five questions above are the most important, these additional questions can also help you make a better decision.
Is the Insurance Company Financially Stable?
Choose an insurer with a strong reputation and the financial strength to pay claims promptly.
Research:
- Customer reviews
- Claim settlement history
- Industry ratings
- Years in operation
Are There Any Discounts Available?
Many insurers offer discounts for:
- Bundling multiple policies
- Safe driving
- Installing security devices
- Paying annually
- Maintaining a claim-free history
Never assume you’ve automatically received every available discount.
Can I Customize My Coverage?
Some insurers allow you to add optional benefits such as:
- Critical illness coverage
- Accidental death benefits
- Roadside assistance
- Rental vehicle reimbursement
- Identity theft protection
Customization helps you pay only for features you actually need.
Common Mistakes Buyers Make
Avoid these costly mistakes when purchasing insurance:
- Choosing the cheapest policy without comparing coverage.
- Failing to read the policy wording.
- Ignoring exclusions.
- Providing inaccurate information.
- Forgetting to review policies annually.
- Buying duplicate coverage.
- Assuming all insurers offer identical protection.
Insurance should be selected based on value—not just price.
Tips for Choosing the Right Insurance Policy
Before making a final decision:
- Compare quotes from multiple insurers.
- Read customer reviews.
- Understand deductibles and exclusions.
- Evaluate claim settlement history.
- Ask about available discounts.
- Review your coverage every year.
- Choose a reputable insurer with strong customer support.
Taking a little extra time today can prevent significant financial problems tomorrow.
Frequently Asked Questions (FAQs)
Why should I ask questions before buying insurance?
Asking questions helps you understand what you’re purchasing, compare policies effectively, avoid hidden costs, and reduce the risk of claim disputes.
What is the most important question to ask?
The most important question is: “What exactly does this policy cover?” Knowing the scope of your coverage is essential for making an informed decision.
Is the cheapest insurance policy always the best?
No. A low premium may come with reduced coverage, higher deductibles, or more exclusions. Always compare the overall value of the policy.
How often should I review my insurance policy?
It’s a good idea to review your policies every year or after major life events such as marriage, buying a home, having children, or starting a business.
Can I change my insurance coverage later?
Many insurers allow policyholders to increase coverage, add riders, or adjust benefits as their needs change. Review your policy’s flexibility before purchasing.
Final Thoughts
Buying insurance is about more than checking a box or meeting a legal requirement—it’s about protecting your financial future. The policy you choose today could have a significant impact on your finances when life takes an unexpected turn.
Before signing any insurance contract, slow down and ask the right questions. Understand what is covered, what isn’t, how much you’ll pay out of pocket, how claims are handled, and whether the policy can grow with your changing needs.
A little preparation now can save you from costly mistakes later. The best insurance policy isn’t simply the cheapest one—it’s the one that provides the right protection, offers reliable customer service, and gives you confidence that you’ll be supported when you need it most.
Take your time, compare your options carefully, and make an informed decision. Your future self—and your loved ones—will thank you