Introduction
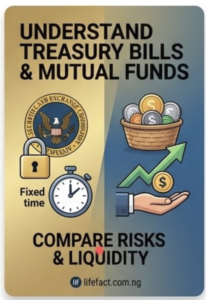
For beginners looking to protect capital while earning interest above traditional savings rates, fixed-income instruments offer a balanced starting point. Understanding how Treasury Bills (T-Bills) and Money Market Funds operate allows new investors to allocate funds effectively based on liquidity needs and risk tolerance.
Comparing Fixed-Income Assets
| Feature | Treasury Bills (T-Bills) | Money Market Mutual Funds |
| Issuer | Central Government | Asset Management Companies |
| Risk Level | Backed by sovereign guarantee (Lowest) | Low risk (Invests in short-term debt) |
| Minimum Capital | Often higher minimum entry | Very low minimum entry threshold |
| Liquidity | Held to maturity (91, 182, 364 days) | High (Withdrawals usually within 24–48 hours) |
1. How Treasury Bills Work
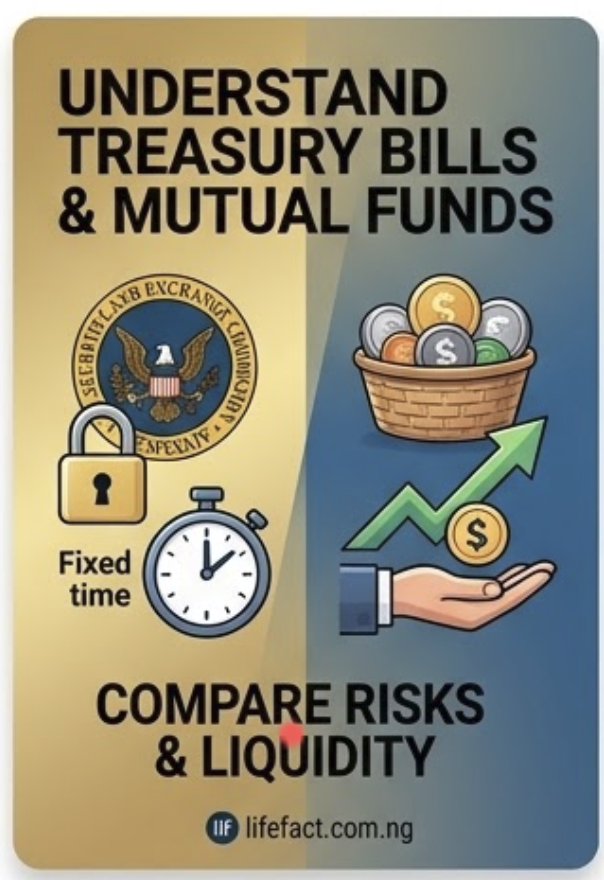
T-Bills are short-term government debt securities issued at a discount and redeemed at full face value upon maturity. The return is guaranteed by the government, making them ideal for long-term capital preservation without equity market exposure.
2. The Flexibility of Money Market Funds
Money Market Funds pool capital from multiple investors to buy a portfolio of short-term debt instruments, including T-Bills, commercial papers, and bank deposits. They offer daily compound interest accrual and allow hassle-free withdrawals, making them a strong alternative to standard bank accounts.
Conclusion
Both Treasury Bills and Money Market Funds serve distinct purposes in a portfolio. Beginners should consider Money Market Funds for accessible liquidity and use T-Bills to lock in fixed returns over longer time horizons.