For many people, reading an insurance policy feels like trying to understand a foreign language. Long paragraphs, legal terminology, technical definitions, exclusions, and fine print can make even the simplest policy seem intimidating.
As a result, many policyholders skip reading their insurance documents altogether. They assume their agent explained everything or believe they’ll only need to look at the policy if something goes wrong.
Unfortunately, that’s one of the biggest mistakes you can make.
When an accident, illness, theft, or natural disaster occurs, your insurance policy becomes one of the most important documents you own. If you don’t understand what’s inside it, you may be surprised to discover that certain situations aren’t covered—or that you’ve misunderstood key conditions.
The good news is that insurance policies are much easier to understand once you know what to look for.
In this guide, we’ll explain how to read an insurance policy step by step, define common insurance terms, highlight the sections you should pay the most attention to, and help you avoid misunderstandings that could cost you money.
Why You Should Read Your Insurance Policy
Many people buy insurance and file the paperwork away without ever opening it again.
That’s risky.
Reading your policy helps you:
- Understand exactly what is covered.
- Learn what isn’t covered.
- Know your responsibilities.
- Avoid claim denials.
- Compare policies more effectively.
- Make informed decisions when renewing coverage.
Your insurance policy is a legal contract. Knowing what’s in it helps you get the full benefit of the protection you’ve paid for.
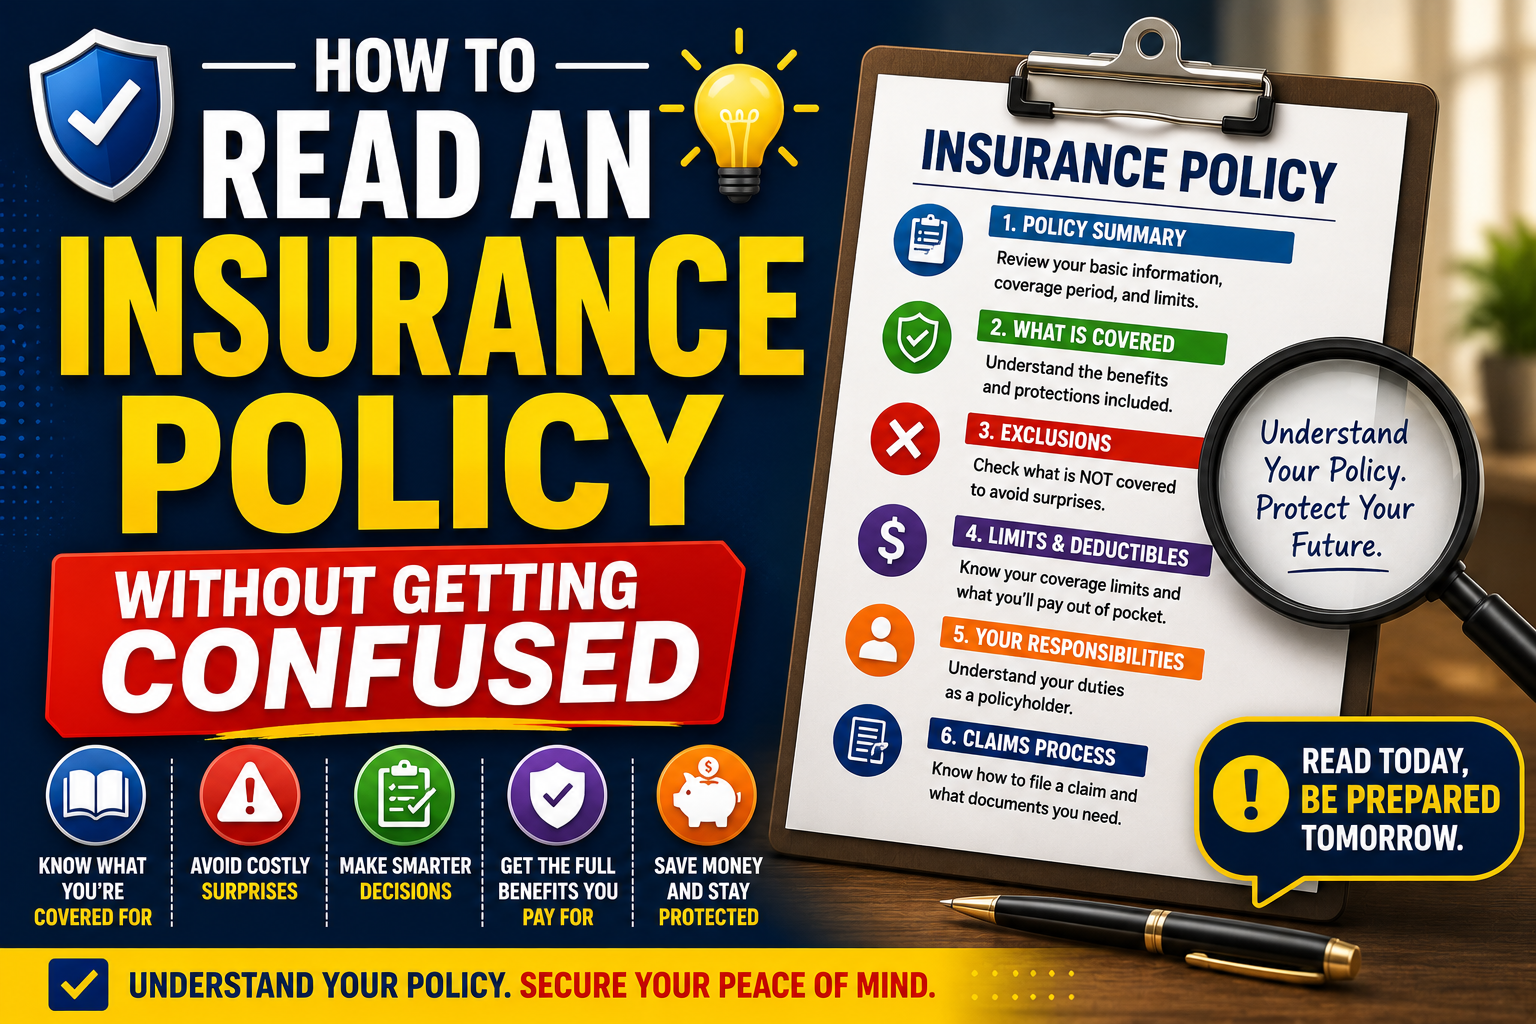
Step 1: Start With the Policy Summary
Most insurance policies begin with a summary page, often called the Declarations Page or Policy Schedule.
This section provides an overview of your policy.
It usually includes:
- Policy number
- Policyholder’s name
- Coverage period
- Covered property or individual
- Coverage limits
- Premium amount
- Deductible
- Endorsements or riders
Before reading the rest of the document, verify that all the information is accurate.
Even small errors—such as an incorrect address or vehicle identification number—can create problems later.
Step 2: Read the Definitions Section
Insurance policies define specific words that may have a different meaning than they do in everyday conversation.
Examples include:
- Insured
- Beneficiary
- Covered loss
- Occurrence
- Deductible
- Premium
- Actual cash value
- Replacement cost
These definitions apply throughout the policy.
If you misunderstand one key definition, it can change the meaning of several other sections.
Never skip the definitions page.
Step 3: Understand What the Policy Covers
The coverage section explains the situations in which the insurance company agrees to pay.
For example:
A home insurance policy might cover:
- Fire
- Theft
- Windstorms
- Lightning
- Vandalism
A health insurance policy may cover:
- Hospitalization
- Surgery
- Doctor visits
- Prescription medication
An auto insurance policy could include:
- Liability
- Collision
- Comprehensive coverage
- Uninsured motorist protection
As you read, ask yourself:
Would this policy protect me in the situations I’m most concerned about?
Step 4: Pay Close Attention to Exclusions
One of the most overlooked sections of any insurance policy is the list of exclusions.
Exclusions explain when the insurer will not pay a claim.
Common exclusions include:
- Flood damage
- Earthquakes
- Wear and tear
- Intentional damage
- Cosmetic repairs
- Illegal activities
- Certain high-risk sports
- Pre-existing medical conditions (depending on the policy)
Understanding exclusions helps prevent unpleasant surprises after filing a claim.
Many disputes occur because policyholders assumed something was covered when it wasn’t.
Step 5: Learn Your Coverage Limits
Every insurance policy has financial limits.
These determine the maximum amount the insurer will pay.
Examples include:
- $500,000 home coverage
- $50,000 personal property coverage
- $100,000 liability coverage
- $1 million life insurance benefit
If your losses exceed these limits, you’ll usually be responsible for the remaining costs.
Make sure your limits are appropriate for your financial situation.
Step 6: Understand Your Deductible
A deductible is the amount you must pay before your insurance begins contributing toward a covered claim.
Example:
Damage totals $10,000
Your deductible is $1,000
Insurance pays $9,000
You pay $1,000
Policies with higher deductibles generally have lower premiums.
Choose a deductible you can comfortably afford during an emergency.
Step 7: Review the Claim Process
Knowing how to file a claim before an emergency occurs can save valuable time.
Look for information about:
- How to report a claim
- Required documentation
- Time limits
- Contact information
- Online claim options
- Emergency procedures
Some insurers require claims to be reported within a specific timeframe.
Missing deadlines may result in claim denial.
Step 8: Check the Conditions
Insurance policies include conditions that both you and the insurer must follow.
Examples include:
- Paying premiums on time
- Reporting losses promptly
- Cooperating during investigations
- Preventing further damage after an incident
- Providing requested documentation
Failure to meet these conditions could affect your claim.
Step 9: Review Any Riders or Endorsements
Many insurance policies include optional additions called riders or endorsements.
These modify your standard coverage.
Examples include:
- Flood insurance
- Jewelry coverage
- Identity theft protection
- Critical illness coverage
- Roadside assistance
- Rental car reimbursement
Review these carefully to understand exactly what additional protection you’ve purchased.
Step 10: Ask Questions About Anything You Don’t Understand
Never feel embarrassed about asking questions.
Insurance professionals expect policyholders to seek clarification.
Ask questions like:
- Can you explain this section in simple terms?
- Does this cover my specific situation?
- Are there any important exclusions?
- What happens if I move or change jobs?
- Can I increase my coverage later?
A five-minute conversation today can prevent expensive misunderstandings later.
Common Insurance Terms Explained
Here are some common terms you’ll encounter:
Premium
The amount you pay for insurance coverage.
Deductible
The amount you pay before insurance contributes to a covered claim.
Coverage Limit
The maximum amount your insurer will pay.
Beneficiary
The person or organization receiving benefits under a life insurance policy.
Exclusion
A situation or event that the policy does not cover.
Claim
A request for payment after a covered event.
Rider (Endorsement)
An optional addition that modifies your policy.
Policyholder
The individual or organization that owns the insurance policy.
Common Mistakes People Make
Avoid these mistakes when reading your insurance policy:
- Reading only the premium amount.
- Ignoring exclusions.
- Skipping the definitions section.
- Forgetting to review coverage limits.
- Assuming all policies are the same.
- Never updating the policy after life changes.
- Failing to ask questions.
Understanding your policy today can prevent disappointment tomorrow.
Tips for Understanding Insurance Faster
Here are practical ways to simplify the process:
- Read the policy in small sections.
- Highlight important terms.
- Make notes as you go.
- Ask your insurance advisor for clarification.
- Compare your policy with others.
- Keep a copy in both digital and printed form.
- Review it annually.
The more familiar you become with your policy, the easier it will be to use when needed.
Frequently Asked Questions (FAQs)
Do I really need to read my insurance policy?
Yes. Your policy explains what is covered, what isn’t, your responsibilities, and how to file a claim. Reading it helps prevent misunderstandings.
What is the most important section of an insurance policy?
The coverage section, exclusions, coverage limits, deductibles, and claim procedures are among the most important sections to understand.
What should I do if I don’t understand my policy?
Contact your insurance provider or advisor and ask them to explain the confusing sections in plain language.
Can my insurance policy change over time?
Yes. Policies may be updated during renewals, through endorsements, or after changes in your personal circumstances.
How often should I review my insurance policy?
At least once a year and whenever you experience major life events such as marriage, purchasing a home, changing jobs, or starting a business.
Final Thoughts
Reading an insurance policy doesn’t have to be overwhelming. While the language may seem technical at first, understanding a few key sections—such as coverage, exclusions, deductibles, limits, and claims procedures—can dramatically improve your confidence and help you make informed decisions.
Remember, insurance is there to protect you, but that protection is only effective if you understand how your policy works. Taking an hour to review your policy today could save you thousands of dollars and countless headaches in the future.
Whenever you’re unsure about a term or condition, ask questions. A reputable insurance professional will be happy to explain the details. The more informed you are, the better prepared you’ll be when life takes an unexpected turn.
Ultimately, the best insurance policy isn’t just the one you buy—it’s the one you fully understand.